The South Tenerife property market remains at high asking-price levels by historical standards, but it is no longer moving in one direction. The latest figures show some coastal areas setting new records, others holding broadly steady, and a few sitting noticeably below their recent peaks.
This market update is based on Idealista asking-price data for August 2026. It covers the four southern municipalities of Adeje, Arona, San Miguel de Abona and Granadilla de Abona, together with the resort and residential areas most relevant to people buying or selling in the south of the island.
One caveat applies throughout. Idealista states that it improved its methodology from July 2026, so comparisons between figures published before and after that point should be treated with some caution. The figures also reflect advertised asking prices, not completed sale prices.
South Tenerife Property Market in 2026: Where Things Stand Now
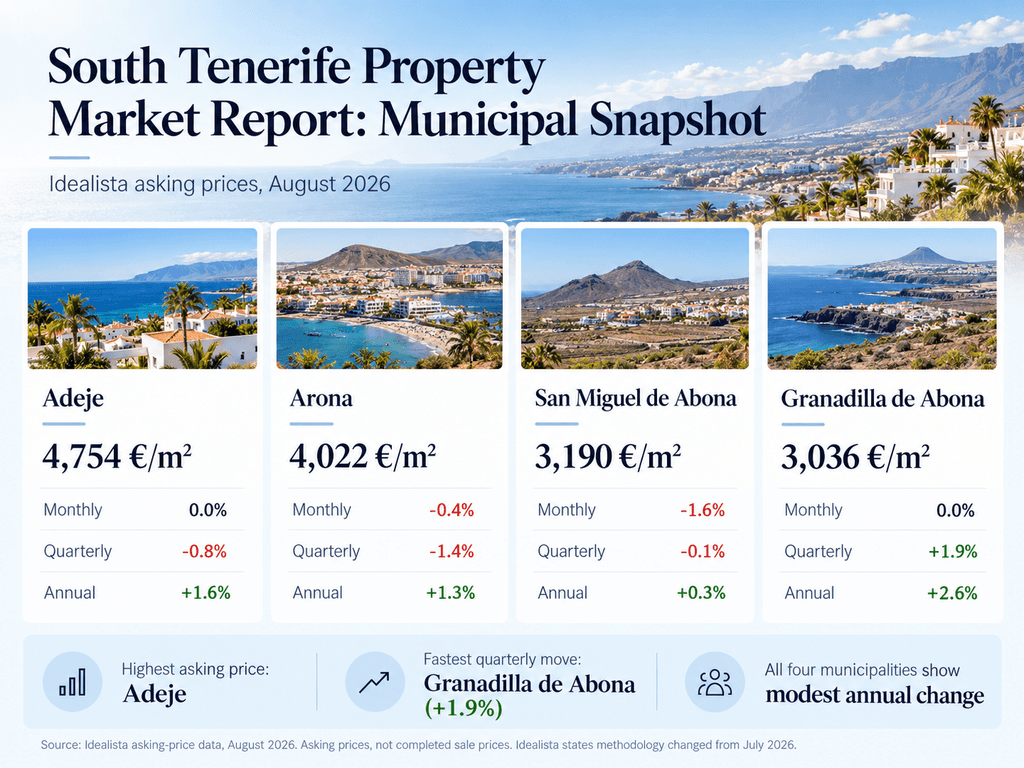
August 2026 asking-price snapshot for Adeje, Arona, San Miguel de Abona and Granadilla de Abona. Source: Idealista.
At the municipality level, the picture is steady rather than dramatic. Annual changes in average asking prices are modest across all four southern municipalities:
| Municipality | August 2026 asking price €/m² | Monthly change | Quarterly change | Year-on-year change |
|---|---|---|---|---|
| Adeje | €4,754/m² | 0.0% | -0.8% | +1.6% |
| Arona | €4,022/m² | -0.4% | -1.4% | +1.3% |
| San Miguel de Abona | €3,190/m² | -1.6% | -0.1% | +0.3% |
| Granadilla de Abona | €3,036/m² | 0.0% | +1.9% | +2.6% |
Adeje and Arona both sit slightly below their historical maximums, recorded in March and February 2026, respectively. San Miguel de Abona is 1.6% below its December 2025 high, while Granadilla de Abona is effectively at its peak, just 0.1% below the April figure.
These averages conceal considerable local variation. Playa Paraíso, Golf del Sur / Amarilla Golf and El Médano all reached new highs in August. Playa de las Américas, by contrast, is now below its level of a year earlier, and Callao Salvaje remains 7.5% below its August 2025 peak.
This is not a broad-based decline. Instead, the asking-price data suggests that the fairly uniform growth seen across much of the south in late 2025 has given way to a more selective market, where location counts for more than it did a year ago.
South Tenerife Property Prices by Area
The table below summarises August 2026 asking prices for the main coastal areas covered in this report.
| Area | August 2026 asking price €/m² | Monthly change | Quarterly change | Year-on-year change |
|---|---|---|---|---|
| La Caleta | €7,500/m² | +0.4% | +0.4% | +4.4% |
| Playa de las Américas | €5,958/m² | -2.1% | -2.3% | -2.1% |
| Costa Adeje | €5,275/m² | -0.6% | -1.8% | +0.5% |
| Los Cristianos | €4,795/m² | +0.2% | -1.0% | +3.4% |
| Playa Paraíso | €4,625/m² | +2.9% | +3.6% | +8.3% |
| Callao Salvaje | €4,057/m² | +0.9% | +1.7% | -7.5% |
| Palm Mar | €4,001/m² | -1.4% | -1.9% | +4.8% |
| Golf del Sur / Amarilla Golf | €3,674/m² | +1.4% | +2.8% | +7.1% |
A brief note on reading these figures. The monthly change compares August with July, the quarterly change compares August with May, and the year-on-year change compares August 2026 with August 2025. Each tells a different story, and a single month’s movement, particularly in smaller markets, should not be read as a trend.
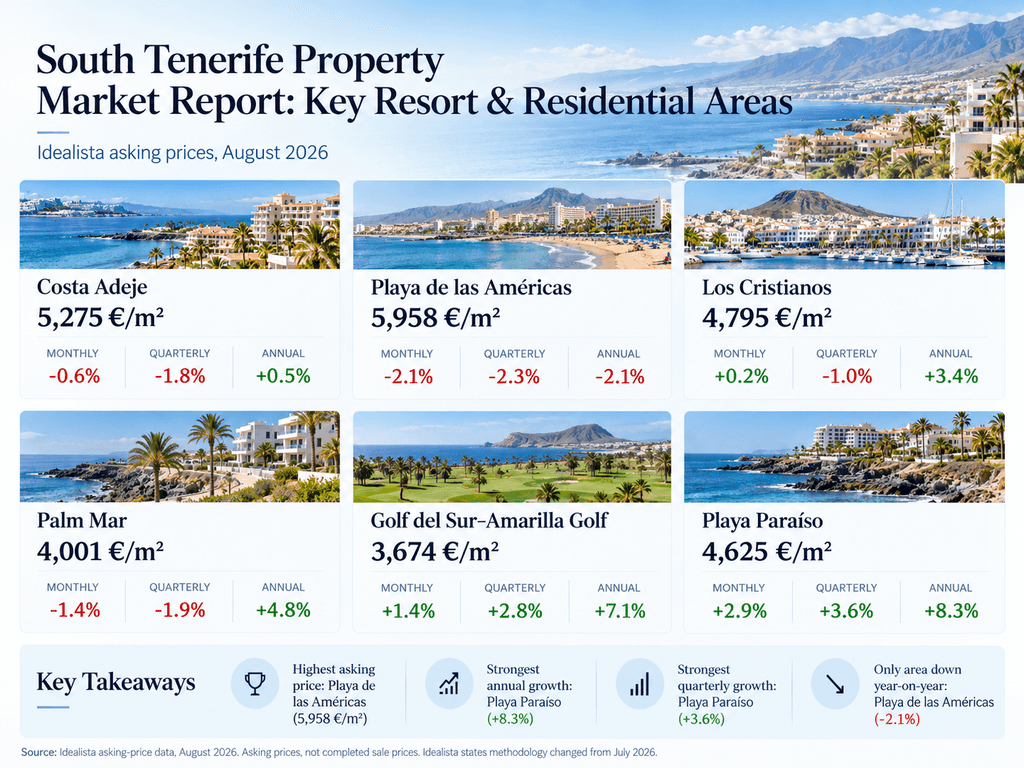
August 2026 asking-price comparison for selected South Tenerife coastal markets. Source: Idealista.
Costa Adeje and the Premium Market
Costa Adeje remains one of the most expensive parts of the island, with an average price of €5,275/m². What has changed is the pace of growth.
In October 2025, asking prices in Costa Adeje were 8.8% higher than a year earlier. By August 2026, that annual rate had moderated to just 0.5%. Prices peaked at €5,388/m² in April and have eased gradually in each month since, leaving the current figure 2.1% below that high. The overall level remains close to where it was a year ago; it is the momentum that has slowed.
Within Costa Adeje, individual micro-markets are behaving quite differently.
La Caleta
La Caleta remains the most expensive area in this report at €7,500/m², up 4.4% on the year and only 1.0% below its April high. Monthly and quarterly movements are both slightly positive. La Caleta’s asking-price data has held up better than the Costa Adeje average over the same period.
Fañabé
Playa de Fañabé, at €6,000/m², is 1.8% lower than a year earlier despite a 1.4% rise in August. Fañabé Alto shows the opposite annual picture: €4,653/m² and 3.4% higher than in August 2025, although its quarterly change of -6.3% indicates a notable easing since May.
San Eugenio Alto
San Eugenio Alto reached a new historical high of €4,746/m² in August, up 1.3% on the month, 3.9% on the quarter and 4.1% on the year. It is one of the more consistent performers within Costa Adeje.
Torviscas
Torviscas Bajo, at €5,333/m², is 1.3% higher year-on-year and unchanged over the quarter. Torviscas Centro y Alto, at €4,095/m², is 6.9% lower than a year ago, one of the weaker annual figures on the Adeje coast.
These are area averages. A frontline apartment with an uninterrupted sea view and a dated unit further back in the same area can differ enormously in value per square metre, and no individual property should be assumed to be worth the statistical average for its area.
Los Cristianos, Playa de las Américas and Arona
Arona provides one of the clearest illustrations of how different local markets can be within the same municipality.
Playa de las Américas
Playa de las Américas remains one of the highest-priced areas in the south, with an average asking price of €5,958/m². Its momentum, however, has changed markedly. In December 2025, prices were 14.9% higher than a year earlier. That annual rate fell steadily through 2026, reaching +0.6% in July and turning negative in August at -2.1%.
The monthly (-2.1%) and quarterly (-2.3%) figures are also negative, and prices now sit 4.5% below the November 2025 peak of €6,238/m². This does not make Playa de las Américas an inexpensive location. It does suggest that advertised prices there may have reached a level where purchasers are becoming more price-sensitive.
Los Cristianos
Los Cristianos, at €4,795/m², remains 3.4% above its August 2025 level. Here too, growth has moderated considerably: at the end of 2025, annual growth was running at over 15%. Prices peaked at €4,915/m² in February and are now 2.4% below that level, with a small 0.2% rise in August.
Arona overall
Across the municipality as a whole, Arona’s average asking price of €4,022/m² is 1.3% higher than a year ago and 2.2% below its February maximum. The municipality figure blends resort areas, residential neighbourhoods and inland locations, which is why it can remain slightly positive even while one of its best-known areas is negative on an annual basis.
Chayofa, a smaller residential area in Arona, recorded a 4.5% monthly rise to €3,250/m² but remains 4.2% lower than a year earlier. In a smaller market with fewer listings, monthly figures can swing more sharply, so these movements should be treated with caution.
Palm Mar, Golf del Sur and the Eastern South
Palm Mar
Palm Mar’s average asking price of €4,001/m² is 4.8% higher than in August 2025 and 1.9% below its May peak of €4,080/m². Monthly figures have been noticeably volatile this year, moving from €3,839/m² in April to €4,080/m² in May, back to €3,897/m² in June and up again to €4,057/m² in July. That pattern is typical of a smaller, more contained market, and the annual figure is a more useful guide than any single month.
Golf del Sur / Amarilla Golf
Golf del Sur / Amarilla Golf stands out in August’s data. Prices reached a new historical high of €3,674/m², up 1.4% on the month, 2.8% on the quarter and 7.1% on the year. The area has followed a fairly steady upward path since spring, and its annual growth rate strengthened in August after several months at around 4%.
At €3,674/m², Golf del Sur remains considerably below the western resort areas on a per-square-metre basis, which may be part of its current appeal.
San Miguel de Abona and Granadilla de Abona
At the municipality level, San Miguel de Abona is broadly flat year-on-year (+0.3%) at €3,190/m². Granadilla de Abona, at €3,036/m², is 2.6% higher than a year earlier and effectively at its historical high.
Within Granadilla, El Médano reached a new high of €4,039/m², with a 4.7% monthly rise and 3.8% annual growth. Los Abrigos is stable at €3,523/m². San Isidro (€2,431/m²) and Granadilla town (€2,195/m²) show stronger annual percentage growth, at 8.8% and 11.0% respectively, but from a much lower base.
These inland and residential areas serve a different buyer profile from the coastal resort markets and should not be treated as direct equivalents of Golf del Sur, Palm Mar or the Adeje coast.
Playa Paraíso and Callao Salvaje: Two Different Trends
Playa Paraíso and Callao Salvaje sit close to one another on the western coast of Adeje, yet their price trends point in opposite directions.
Playa Paraíso reached a new historical high of €4,625/m² in August, up 2.9% on the month, 3.6% on the quarter and 8.3% on the year. Although annual growth has moderated from the exceptional rates of late 2025, when it exceeded 20%, the area remains one of the stronger performers in the south.
Callao Salvaje tells a different story. Its average asking price of €4,057/m² is 7.5% below its August 2025 historical high of €4,385/m². Short-term figures have improved slightly, with rises of 0.9% on the month and 1.7% on the quarter, but the area has not recovered its previous level.
The contrast is clear in the current data. Playa Paraíso is at a new asking-price high, while Callao Salvaje remains below its August 2025 level. This illustrates how neighbouring markets can move in different directions even over the same period.
Several factors can cause this kind of divergence, including the mix of properties on the market at any given time, the arrival of new builds or refurbished stock, and the quality of individual complexes. The published data does not tell us which of these is at play, but it is a useful reminder that proximity alone does not guarantee similar performance.
Are South Tenerife Property Prices Still Rising?
There is no single answer.
Some areas remain in a clear upward trend, notably Playa Paraíso, Golf del Sur / Amarilla Golf, San Eugenio Alto and El Médano, all of which recorded new highs in August. Others, such as La Caleta, Los Cristianos and Palm Mar, remain above their year-ago levels but below recent peaks, suggesting a degree of stabilisation. A smaller group, including Playa de las Américas, Callao Salvaje and Torviscas Centro y Alto, are below where they were a year ago.
It is also worth remembering what this data measures. Asking prices show what sellers hope to achieve. They do not show the final negotiated price, how long properties take to sell, or how many sales are completing. A rising average can coexist with increased negotiation, and a falling one can reflect a change in the type of property being listed rather than a fall in property values.
What Is Driving Demand in South Tenerife?
The fundamentals behind demand in the south of the island are well established.
South Tenerife’s year-round climate continues to support international demand, including buyers looking for second homes, extended winter stays and permanent or semi-permanent residence. Lifestyle appeal plays a significant part, with the coast offering beaches, golf, marinas, restaurants and walking routes within a relatively compact area.
Limited supply is another important factor. Prime coastal land in the established resort areas is scarce, and opportunities to build new frontline developments are few. This tends to support values in the most sought-after locations, even when wider growth slows.
The south also benefits from established tourism infrastructure, including good air connections, healthcare facilities and international services. Modern developments and new-build property can appeal to purchasers looking for contemporary specifications and communal facilities. Where new stock comes to market, it can also influence local asking-price averages.
South Tenerife also attracts people planning longer stays, including relocation, remote working and extended winter use. These different profiles do not affect every area equally, which may partly contribute to the local variation seen in the data.
What This Market Means for Buyers
For anyone looking to buy, the August data reinforces the value of examining specific locations rather than relying on headline figures.
Compare by exact location. A municipality average for Adeje or Arona combines very different markets. The figures for La Caleta, Torviscas Centro y Alto and Callao Salvaje, all within Adeje, show how wide that range can be.
Use €/m² carefully. Price per square metre is a useful starting point, but it does not account for views, orientation, terrace size, parking, storage, communal facilities, the condition of the building or the quality of the complex. Two apartments with the same €/m² can represent very different value.
Consider condition and refurbishment costs. A lower asking price may reflect a property that needs substantial work. Factor this into any comparison.
Do not assume every asking price reflects market value. Prices are set by sellers and can vary widely. In areas where momentum has slowed, some listings may be priced more ambitiously than recent conditions support.
Prepare the practical steps early. Obtaining your NIE Number in Spain, arranging finance where needed and appointing an independent lawyer before making an offer can make the process considerably smoother. Our guides to Buying Property in Tenerife and Legal Checks When Buying Property in Tenerife cover these steps in more detail.
When you are ready to compare current listings, you can browse our Properties for Sale in Tenerife.
What This Market Means for Sellers
For owners considering a sale, a more differentiated market places greater emphasis on pricing and presentation.
Get the initial price right. In areas where prices have eased from recent peaks, prospective purchasers are likely to compare listings more carefully. A property launched significantly above comparable listings may attract less interest, and later reductions can affect how it is perceived.
Base valuation on genuine comparables. A realistic property valuation should consider similar properties in the same area and, ideally, the same type of complex, rather than a municipality or area-wide average.
Allow for negotiation. The price ultimately agreed may differ from the advertised figure, and the extent of negotiation can vary between areas and property types.
Invest in condition and presentation. Well-maintained properties, clear information, professional photography and a floor plan help people understand what they are paying for. In a selective market, presentation can make a meaningful difference.
Ensure appropriate marketing exposure. South Tenerife properties are marketed to both local and international audiences, so effective exposure beyond the local market can be important.
None of these steps guarantee a quick sale, but a well-considered pricing strategy gives a property the best opportunity to attract serious interest.
South Tenerife Property Market Outlook for the Rest of 2026
Rather than predicting where prices will go, it is more useful to identify the indicators we will be watching over the coming months.
Asking-price direction. Whether areas such as Playa de las Américas and Costa Adeje stabilise, and whether the current highs in Playa Paraíso and Golf del Sur are sustained.
Inventory and supply. Changes in the number and type of properties coming to market, which can influence area averages.
Buyer demand. Whether enquiry and purchasing activity remains strong across the different South Tenerife locations as the year progresses.
Mortgage conditions. Lending conditions for both resident and non-resident purchasers.
New-build availability. The volume and location of new developments, which can shift averages in individual areas.
Time on market and negotiation. How long properties take to sell and how far agreed prices differ from asking prices. Neither is captured in asking-price data, but both are important signs of underlying market strength.
South Tenerife remains a high-value property market. The August data does not point to a broad downturn, but it does suggest greater differentiation between locations than during the stronger, broad-based growth seen earlier in the cycle. For buyers and sellers alike, understanding the specific area, and the specific property, matters more than ever.
Source and methodology note: All figures in this report are average asking prices per square metre for properties advertised for sale, taken from Idealista’s published reports for August 2026. They are not completed transaction prices. Idealista states: “Since July 2026 we have improved our methodology.” Comparisons between data published before and after July 2026, including year-on-year changes, should therefore be treated with appropriate caution.
